Tag: preventive care

  • Medicare Diabetes Prevention Program in 2026: Who Qualifies and How to Enroll

    Published: September 24, 2026 · Last updated: September 24, 2026

    Quick answer

    The Medicare Diabetes Prevention Program (MDPP) offers a year of structured lifestyle support at no cost to eligible people with Medicare Part B. You need a qualifying blood test, the required BMI, and no prior diagnosis of type 1 or type 2 diabetes or end-stage renal disease. An approved supplier must deliver the program. Check the official Medicare eligibility and cost rules.

    Two 2026 changes are worth checking: the old once-per-lifetime limit has ended, and approved self-paced online programs are now a covered option. However, self-paced and live classes follow different delivery rules. This guide explains what to ask before you enroll.

    A clinician says your blood sugar is in the prediabetes range. You leave with advice to eat differently and move more—but little help turning that advice into a Tuesday afternoon. MDPP is designed to provide that practical support. The challenge is finding the right program and confirming that it is the Medicare benefit, not a separate paid wellness subscription.

    Key takeaways

    • Check the actual lab result. MDPP’s fasting-glucose threshold differs from the usual prediabetes threshold.
    • Ask about current rules. Older pages may still say you can participate only once in your life.
    • Confirm the supplier and format. A prevention app or a CDC-recognized class is not automatically a Medicare-enrolled MDPP supplier.
    • Choose support you can use. Transportation, class timing, technology, language, and coach access matter as much as a program’s name.

    What changed in the Medicare Diabetes Prevention Program in 2026?

    First, the Consolidated Appropriations Act, 2026 removed the once-per-lifetime limit on February 3, 2026. CMS says this applies to both Original Medicare and Medicare Advantage. Previous participation therefore does not, by itself, rule you out. You still need to meet the applicable eligibility requirements. Ask the supplier how a new course fits your previous service dates.

    Second, CMS added coverage for asynchronous—self-paced, non-live—online delivery starting January 1, 2026, through December 31, 2029. Live video classes remain a different format. These are earlier-2026 changes, not a new law announced this week. We checked them against the CMS MDPP FAQ, last modified September 22, 2026.

    Who qualifies for the Medicare Diabetes Prevention Program?

    You need Part B coverage and must meet the following conditions. One qualifying test is enough for the blood-test requirement; you do not need all three. The test must fall within the 12 months before your first core session. The supplier verifies your eligibility using the Medicare coverage criteria.

    On a small screen, swipe the table sideways if needed.

    MDPP eligibility: what to have ready
    RequirementCurrent rulePractical check
    Medicare coveragePart B; Medicare Advantage also covers this benefit.Have your coverage details ready. Ask an Advantage plan about its network.
    One qualifying lab testA1C 5.7–6.4%; or fasting plasma glucose 110–125 mg/dL; or two-hour oral glucose tolerance test 140–199 mg/dL.Keep the result, test type, and date—not just a note saying “prediabetes.”
    TimingQualifying test within 12 months before the first core session.Check the planned start date, not only the day you call.
    Body mass indexBMI at least 25, or at least 23 for Asian participants.Ask what height and weight documentation the supplier needs.
    Medical historyNo prior type 1 or type 2 diabetes diagnosis or end-stage renal disease.Discuss your history with your clinician and supplier. Prior gestational diabetes is a different category.

    The easy-to-miss difference: 100 versus 110

    NIDDK lists the usual fasting-glucose prediabetes range as 100–125 mg/dL. MDPP’s qualifying fasting result starts at 110 mg/dL. Thus, a fasting result of 105 alone does not meet that particular MDPP route. However, a qualifying A1C or two-hour test may meet the lab requirement. These tests do not always identify the same people. See NIDDK’s diagnostic ranges and Medicare’s separate benefit thresholds.

    This is a coverage distinction, not a reason to dismiss an abnormal result or order extra tests yourself. Ask your clinician to interpret the results you already have. For related billing questions, see our guide to metabolic blood tests and insurance.

    What does the Medicare Diabetes Prevention Program cost?

    Medicare says you pay nothing for MDPP if you qualify. Use an approved Medicare supplier. If you have Medicare Advantage, confirm any in-network requirement before starting. A commercial app subscription, gym membership, or separate nutrition package is not automatically this covered service. Ask the organization to distinguish MDPP sessions from optional purchases. The official benefit page is the starting point for that conversation.

    Likewise, a blood test is a separate service. Medicare covers eligible diabetes screenings at no charge when the provider accepts assignment, subject to its screening rules. That does not make every office visit or lab panel free. Before testing, ask what the clinician is ordering and how the lab will bill it. See Medicare’s diabetes-screening benefit.

    In person, live video, or self-paced online?

    The word “online” can hide two very different experiences. A scheduled video group is distance learning: everyone attends live. In contrast, an asynchronous program lets you work through content on your own schedule. Under current CMS delivery rules, you can combine in-person and live distance-learning sessions, but you cannot mix self-paced online delivery with those live formats within the same set of MDPP services.

    Choose a format you can sustain
    FormatWhat it involvesAsk before enrolling
    In personScheduled classes with a coach and peers.Where are sessions? What happens if transport or illness prevents attendance?
    Live distance learningScheduled live sessions remotely; can combine with in-person sessions.Which device and connection are needed? Is technical help available?
    Self-paced onlineNon-live lessons on your schedule, with human coach interaction offered.How do I contact my coach? How are participation and weight documented?

    Self-paced does not mean “just watch videos.” CMS requires suppliers to offer live human coach interaction during weeks when a participant engages with content. Two-way email or text can count; a chatbot does not. Ask for a concrete example of that support. Virtual delivery options currently extend through December 31, 2029; availability still depends on participating suppliers. See the CMS online-delivery FAQ.

    What happens during the year?

    Medicare covers up to 22 sessions within 12 months: up to 16 weekly core sessions in the first six months, followed by six monthly sessions. The focus is lasting changes in food choices, activity, and weight management—not a crash diet. Medicare describes trained coaching and peer support for live formats. CDC gives practical examples such as adapting familiar foods and planning around holidays. See Medicare’s session outline and CDC’s explanation of the program.

    You do not have to achieve 5% weight loss to keep receiving the covered core and maintenance sessions during this service period. CMS explicitly says suppliers must provide them to eligible participants regardless of reaching that milestone. However, Medicare pays for sessions attended, and the 12-month window still matters. Discuss missed sessions early rather than assuming they automatically roll over. CMS explains attendance and continuation rules here.

    How to enroll in the Medicare Diabetes Prevention Program

    1. Gather the basics

    Find your Medicare coverage details, qualifying lab report and date, current height and weight information, and any previous MDPP dates. Then ask your clinician whether the program fits your health needs. CMS does not require an MDPP referral, but a provider referral is needed for tests billed under the diabetes-screening benefit. Do not confuse the two. Source: CMS referral guidance.

    2. Find an approved supplier

    Start with the “Find providers” tool on Medicare’s MDPP page. Search by location and filter by class format. Community organizations may offer the benefit as well as health care providers. If nearby options are limited, check approved online programs rather than assuming a commercial app qualifies.

    3. Confirm coverage before the first session

    Ask the supplier to verify your eligibility and confirm that it will provide and bill MDPP. If you have Medicare Advantage, contact the plan as well. Keep the person’s name, date, and any reference number. If you participated before, mention that immediately and ask about the current repeat-participation rules.

    4. Check the everyday details

    Request the start date, schedule, language options, accessibility support, make-up policy, and coach contact method. Also ask how the program documents weight and attendance. For online classes, establish who helps with technical problems. These questions test whether the program fits your life—not whether you have enough willpower.

    5. Save your confirmation and check any bill

    Keep a copy of what the supplier confirms about coverage and optional charges. If a bill arrives unexpectedly, ask which service it covers and whether it is MDPP or something separate. Then contact the supplier and, where relevant, your plan before assuming the charge is correct. Do not ignore a bill while you investigate it.

    What benefit is supported by research?

    The landmark Diabetes Prevention Program trial randomized 3,234 adults at high risk of diabetes. Over an average 2.8 years, intensive lifestyle support reduced diabetes incidence by 58% relative to placebo. Rates were 4.8 versus 11.0 cases per 100 person-years. That is a relative reduction in a studied population—not a promise that every enrollee’s personal risk falls by 58%. Read the original 2002 trial abstract.

    Importantly, that trial was not a direct test of every current MDPP supplier or the new self-paced format. Its intervention, participants, and follow-up differ from routine Medicare delivery. It supports structured lifestyle prevention, but does not prove all class formats perform equally. For broader background, see NIDDK’s DPP research overview.

    A device is also a different intervention from a year of coaching. If you are considering buying a sensor instead, our CGM and weight-loss evidence review separates device effects from bundled lifestyle support.

    Frequently asked questions

    Can I join again if I have already used MDPP?

    Prior participation is no longer a lifetime exclusion. The limit ended on February 3, 2026. However, eligibility and the rules for a course of services still apply. Ask the supplier to verify your record and proposed start date; do not interpret this as unlimited overlapping sessions. Source: CMS.

    Does Medicare Advantage cover the program?

    Yes. CMS says an Advantage plan must offer MDPP even if it has a similar supplemental prevention benefit. You may need an in-network supplier, so confirm this with your plan. CMS explains the distinction; Medicare explains network considerations.

    What if I already have type 2 diabetes?

    MDPP is not the entry program for someone with established type 2 diabetes. Ask instead about diabetes self-management training. That separate Part B benefit requires a provider order and a diabetes diagnosis. Under Original Medicare, its usual cost is 20% of the approved amount after the Part B deductible; other coverage can affect what you owe. See Medicare’s self-management training rules.

    What if diabetes develops after I start?

    CMS says participants who develop diabetes while receiving MDPP can continue the services for which they remain eligible. Tell your clinician and supplier so your diabetes care is addressed too. Continuing prevention-program sessions is not a substitute for appropriate treatment. Source: CMS beneficiary FAQ.

    Does MDPP approval also cover weight-loss medication?

    No—do not use approval for a lifestyle program as proof of drug coverage. These are different benefits with different requirements. For that separate question, see our Medicare Wegovy and GLP-1 coverage guide, and confirm current drug coverage with your plan.

    Sources and further reading

    1. Medicare.gov: MDPP eligibility, costs, session structure, and supplier search.
    2. CMS: MDPP frequently asked questions, including 2026 repeat-participation and online-delivery rules.
    3. CDC: Preventing Type 2 Diabetes with Medicare.
    4. NIDDK: Diabetes Tests & Diagnosis.
    5. Medicare.gov: Diabetes screenings.
    6. Medicare.gov: Diabetes self-management training.
    7. Diabetes Prevention Program Research Group. NEJM, 2002. DOI: 10.1056/NEJMoa012512.
    8. NIDDK: Diabetes Prevention Program research overview.

    How this guide was prepared

    This is a practical coverage guide, not a systematic review or a comparison of individual suppliers. We checked the official Medicare, CMS, CDC, and NIDDK pages linked above on September 24, 2026. For the trial’s numerical results, we used its PubMed abstract; we did not reanalyze participant data. In addition, current CMS and Medicare guidance took priority over older descriptions of the lifetime limit. Supplier availability, plan networks, and future rules may change.

    Update history: September 24, 2026 — First publication; includes the 2026 repeat-participation change and the distinction between live and self-paced delivery.

    Written and edited by: Denny Jaeyong Choi (JD), INSEAD MBA

    Medical information notice: This article provides general health and coverage information, not personal medical advice or a determination of insurance eligibility. Discuss test results and care with a qualified clinician. Confirm coverage and enrollment with Medicare, your plan, and the approved supplier.
  • Metabolic Syndrome Blood Tests: What Insurance Covers in 2026

    Metabolic Syndrome Blood Tests: What Insurance Covers in 2026

    Quick answer: Metabolic syndrome blood tests are not a single special panel. It combines waist circumference and blood pressure with three laboratory measurements: fasting glucose, triglycerides, and HDL cholesterol. U.S. insurance may cover some of these as preventive screening when you meet plan criteria and use in-network care. The same tests may be subject to a deductible, copay, or coinsurance when they are ordered to evaluate symptoms or monitor a known condition. Confirm the reason for the order, the laboratory network, and your estimated cost before the blood draw.

    Published: September 13, 2026 · Last reviewed: September 13, 2026
    Written and edited by: Denny Jaeyong Choi (JD), INSEAD MBA

    Key takeaways

    • Metabolic syndrome is generally identified when at least three of five risk factors are present. Only three of those five require a blood sample.
    • A fasting glucose test is not the same as an A1C. Fasting glucose usually requires at least eight hours without food; an A1C usually does not.
    • “Preventive” does not automatically mean every related lab is free. Network status, age and risk criteria, the diagnosis attached to the order, and services performed during the same visit can affect cost-sharing.
    • Original Medicare Part B covers eligible diabetes screening up to twice per year and a cardiovascular lipid screening once every five years, with no charge when coverage rules are met and the provider accepts assignment.
    • The best cost-control step is to ask for the exact test names, the laboratory, and a pre-service estimate before your appointment.

    What are metabolic syndrome blood tests?

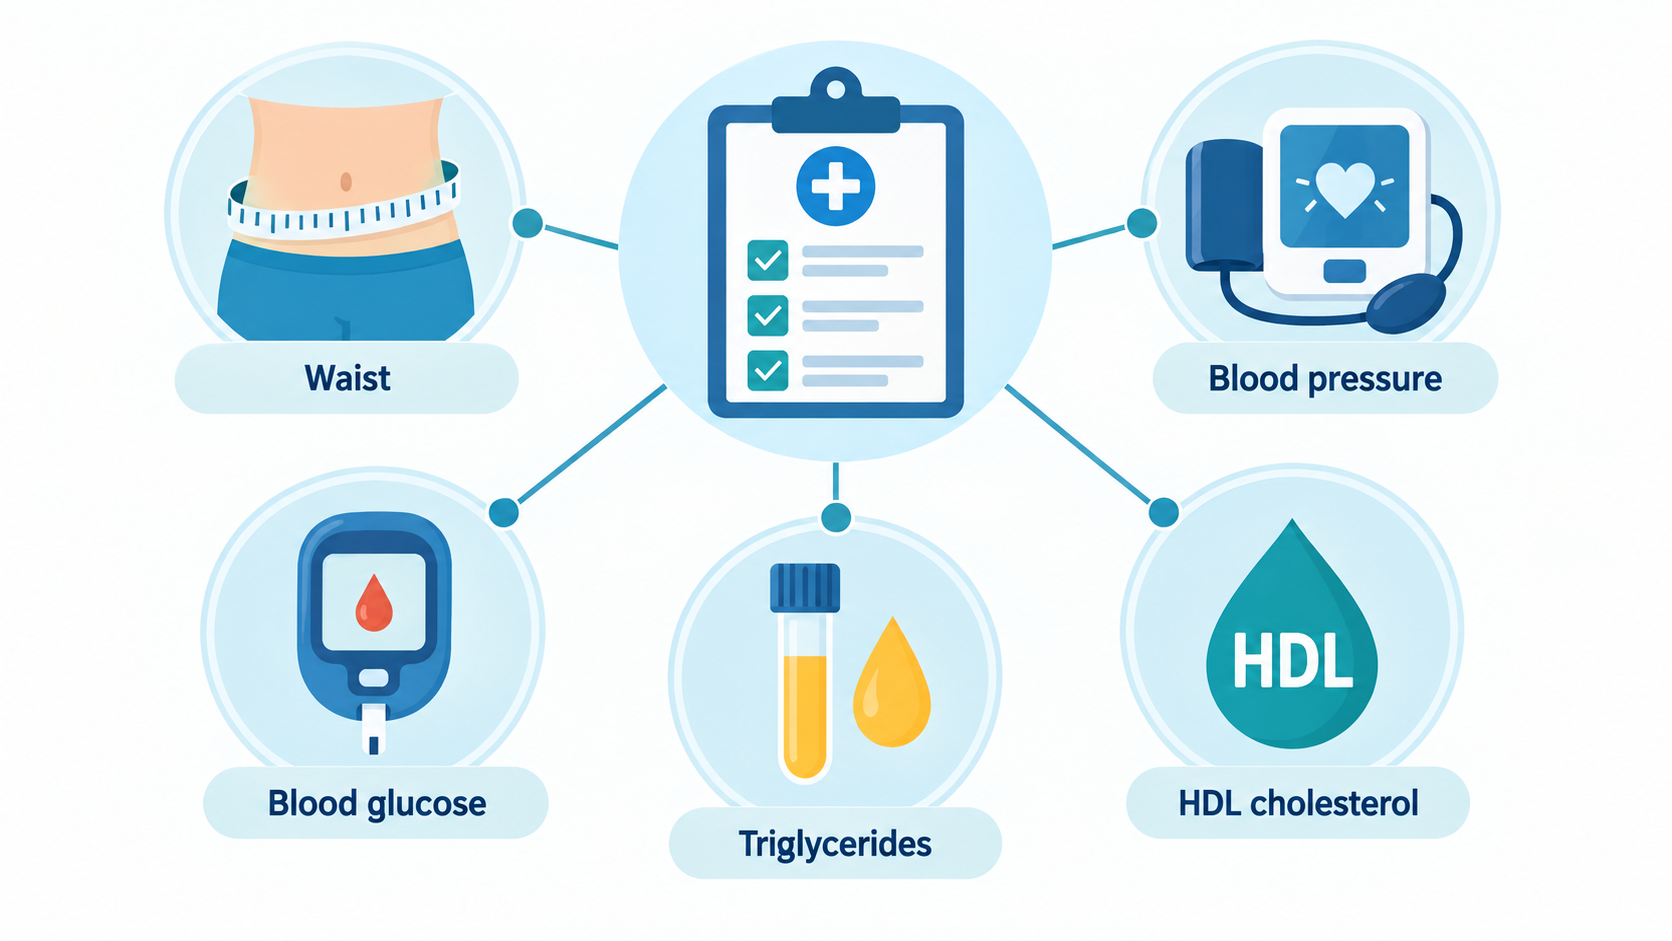
    Metabolic syndrome is a cluster of findings that together raise the risk of cardiovascular disease, type 2 diabetes, stroke, and other health problems. The National Heart, Lung, and Blood Institute (NHLBI) says a clinician may diagnose it when three or more of five conditions are present. Those conditions are a large waistline, elevated blood pressure, elevated fasting glucose, elevated triglycerides, and low HDL cholesterol. Our separate guide explains the five metabolic syndrome criteria in more detail.

    The phrase “metabolic syndrome blood panel” can therefore be misleading. There is no single universal panel with that name. A clinician usually combines a physical assessment with a glucose test and a lipid panel. The exact order may vary based on your history, medications, symptoms, prior results, and what your insurance plan covers.

    Five metabolic syndrome measurements: waist circumference, blood pressure, blood glucose, triglycerides, and HDL cholesterol
    Metabolic syndrome is assessed using five measurements; insurance coverage depends on why each test is ordered and how it is billed.

    The five measurements, in plain English

    MeasurementCommon threshold used for metabolic syndromeDoes it require fasting?Typical insurance question
    Waist circumferenceMore than 40 in (102 cm) for men or 35 in (88 cm) for women; ethnicity-specific cutoffs may differNoUsually part of an office assessment rather than a separate lab claim
    Blood pressure130/85 mm Hg or higher, or treatment for high blood pressureNoScreening may be preventive; evaluation or management can generate a visit charge
    Fasting glucose100 mg/dL or higher, or treatment for elevated glucoseYes, when specifically ordered as fasting plasma glucoseAsk whether the order is preventive diabetes screening or diagnostic testing
    Triglycerides150 mg/dL or higher, or treatment for elevated triglyceridesFollow the ordering clinician’s instructionsOften included in a lipid panel; preventive frequency limits may apply
    HDL cholesterolBelow 40 mg/dL for men or below 50 mg/dL for women, or treatmentFollow the ordering clinician’s instructionsUsually included in a lipid panel rather than billed alone
    Thresholds summarize commonly used adult criteria. Clinicians may apply population-specific waist cutoffs and interpret results in context.

    The NHLBI diagnostic guide describes these measurements and notes that waist cutoffs may vary by race and ethnicity. One result also does not diagnose diabetes by itself in an asymptomatic person. The National Institute of Diabetes and Digestive and Kidney Diseases (NIDDK) explains that abnormal diabetes testing is usually confirmed with a second measurement.

    Which metabolic syndrome blood tests should you ask about?

    1. Fasting plasma glucose

    This is the glucose measurement used in the classic metabolic syndrome criteria. NIDDK says it is usually performed in the morning after at least eight hours of fasting, with only sips of water. A result from a home glucose meter cannot diagnose diabetes.

    2. A lipid panel

    A standard lipid panel commonly reports triglycerides and HDL cholesterol, as well as total and LDL cholesterol. Triglycerides and HDL are the two components used for metabolic syndrome. LDL is important for cardiovascular risk management, but it is not one of the five metabolic syndrome criteria.

    3. A1C, when clinically appropriate

    An A1C estimates average blood glucose over roughly three months and usually does not require fasting. It can screen for prediabetes or diabetes, but it does not directly replace fasting glucose in every definition of metabolic syndrome. It can also be less reliable in some situations, including certain anemias, hemoglobin variants, recent blood loss, kidney failure, or pregnancy. Your clinician should decide whether fasting glucose, A1C, or another test best answers the clinical question.

    A continuous glucose monitor is not normally required to diagnose metabolic syndrome. If you are comparing self-pay options for glucose tracking, see our guide to CGM cost without insurance.

    Will insurance cover metabolic syndrome blood tests?

    Often, at least part of the evaluation is covered—but “covered” and “free” are not the same. HealthCare.gov says Marketplace plans and many other plans cover specified preventive services without copayment or coinsurance, generally when the service is delivered by an in-network provider. Its adult list includes blood pressure screening, cholesterol screening for eligible adults, type 2 diabetes screening for certain adults with overweight or obesity, and obesity screening and counseling. The page also warns that zero-dollar coverage is not guaranteed in every case.

    The U.S. Preventive Services Task Force currently recommends screening asymptomatic adults ages 35 to 70 who have overweight or obesity for prediabetes and type 2 diabetes. Yet your plan document, network rules, and the way the claim is coded still matter. A plan may treat a test differently if you already have diabetes, high cholesterol, hypertension, symptoms, an abnormal prior result, or a medication that needs monitoring.

    Preventive screening versus diagnostic testing

    This distinction causes many surprise bills:

    • Preventive screening looks for disease in someone without symptoms who meets guideline and plan criteria.
    • Diagnostic testing evaluates a symptom, abnormal result, suspected condition, or known disease.
    • Monitoring follows an already diagnosed condition or treatment.

    The same laboratory test can fall into any of these categories. The difference may affect deductible and coinsurance. The ordering clinician—not the patient—selects the diagnosis and reason for the order, and the insurer adjudicates the claim. You should not ask anyone to change accurate coding simply to avoid a charge. Instead, ask for an estimate based on the clinically correct order.

    What does Medicare cover for metabolic syndrome blood tests?

    Original Medicare handles the glucose and lipid portions under separate benefits:

    • Diabetes screening: Medicare Part B covers eligible glucose screenings when a clinician determines that you are at risk. Medicare lists high blood pressure, abnormal cholesterol or triglycerides, obesity, and a history of high blood sugar among qualifying risk factors. Covered tests may include fasting or nonfasting glucose, A1C, or another Medicare-approved glucose test. Medicare.gov states that eligible beneficiaries can receive up to two screenings per year and pay nothing when the provider accepts assignment.
    • Cardiovascular screening: Part B covers blood tests for cholesterol, lipid, and triglyceride levels once every five years. Medicare.gov says you pay nothing when the provider accepts assignment.
    • Annual Wellness Visit: the visit includes blood pressure, weight, BMI or waist measurement when appropriate, and a personalized prevention plan. However, the visit itself does not automatically bundle every laboratory test. Labs must qualify under their own coverage rules, as the CMS guidance makes clear.

    Medicare Advantage plans must cover Medicare-covered services but can use plan networks and administrative rules. Call the number on your plan card for the lab network and expected cost. If an abnormal glucose result identifies prediabetes, some beneficiaries may also qualify for the Medicare Diabetes Prevention Program.

    A five-minute call that can prevent a surprise bill

    Call your insurer before the blood draw. Use the exact test names on the order and ask:

    1. Is the ordering clinician in network?
    2. Is the laboratory in network? Hospital-owned labs and independent labs may have different rates.
    3. Are fasting plasma glucose, A1C, and the lipid panel covered as preventive screening for me?
    4. Do age, risk-factor, or frequency rules apply?
    5. Will I owe a deductible, copay, or coinsurance if the order is diagnostic or for monitoring?
    6. Do I need a referral or prior authorization?
    7. Can you give me a call reference number or written estimate?

    You can also ask the clinic: “Which tests are being ordered, which lab will process them, and can you send me the order so I can request a plan estimate?” If you are paying cash, request the self-pay price in writing and compare it with your expected in-network cost. A low cash price may not count toward your deductible.

    How to prepare for metabolic syndrome blood tests

    • Confirm whether fasting is required. If fasting plasma glucose is ordered, NIDDK advises at least eight hours without food; follow the lab’s exact instructions.
    • Ask about medications. Do not stop prescribed medicine on your own. Ask whether to take morning medicines and supplements before testing.
    • Bring prior results. Trends can be more informative than one isolated value.
    • Wear practical clothing. A correct waist measurement is taken around the abdomen, not over a bulky jacket.
    • Rest before blood pressure measurement. Tell the clinician about caffeine, exercise, smoking, pain, or stress that may affect the reading.

    A complete assessment should not reduce you to a single number. Our complete obesity evaluation guide explains how history, body measurements, complications, sleep, medications, barriers, and personal goals fit together.

    What if metabolic syndrome blood tests are abnormal?

    One abnormal value is a reason for a clinical conversation, not a self-diagnosis. Your clinician may repeat a measurement, confirm that the test was performed correctly, assess medications and other causes, or order additional tests. Metabolic syndrome is a risk framework; each component also deserves individual management.

    If three or more criteria are present, the next step is usually to address overall cardiovascular and diabetes risk rather than chase a label. That can include nutrition, physical activity, sleep, tobacco cessation, weight management, and treatment of blood pressure, glucose, or lipids when appropriate. If cost or coverage blocks care, tell the clinic. A feasible plan may use an in-network lab, covered preventive services, staged testing, or a different follow-up schedule.

    Frequently asked questions

    Is there one blood test for metabolic syndrome?

    No. Assessment combines waist circumference, blood pressure, fasting glucose, triglycerides, and HDL cholesterol. The last three involve laboratory testing.

    Do I need to fast?

    You need to fast for a fasting plasma glucose test. An A1C does not usually require fasting. Lipid-testing instructions can vary, so follow the order and laboratory directions rather than guessing.

    Will an annual physical include these labs for free?

    Not necessarily. Your plan may cover specific preventive screenings, but the office visit and each laboratory service have separate coverage rules. Original Medicare’s Annual Wellness Visit is not the same as a routine physical and does not automatically include clinical laboratory tests.

    Can I use home readings?

    Home blood pressure logs can provide useful context, but diagnosis should be confirmed with a clinician using a validated device and proper technique. A consumer glucose meter or CGM cannot by itself diagnose diabetes or metabolic syndrome.

    Bottom line

    Metabolic syndrome blood tests are only part of the workup: clinicians also measure waist and blood pressure, then check fasting glucose, triglycerides, and HDL. The billing can be less simple. Ask whether each service is preventive or diagnostic, verify both clinician and lab networks, and request an estimate. That preparation is often more useful than searching for a generic “metabolic panel,” which may not contain the tests needed to evaluate metabolic syndrome.

    Sources and further reading

    Medical and insurance information notice: This article provides general educational information and does not replace individualized medical advice, diagnosis, treatment, or a coverage determination from your insurer. Benefits, networks, billing rules, and clinical recommendations can change. Confirm current details with your clinician, laboratory, and health plan.